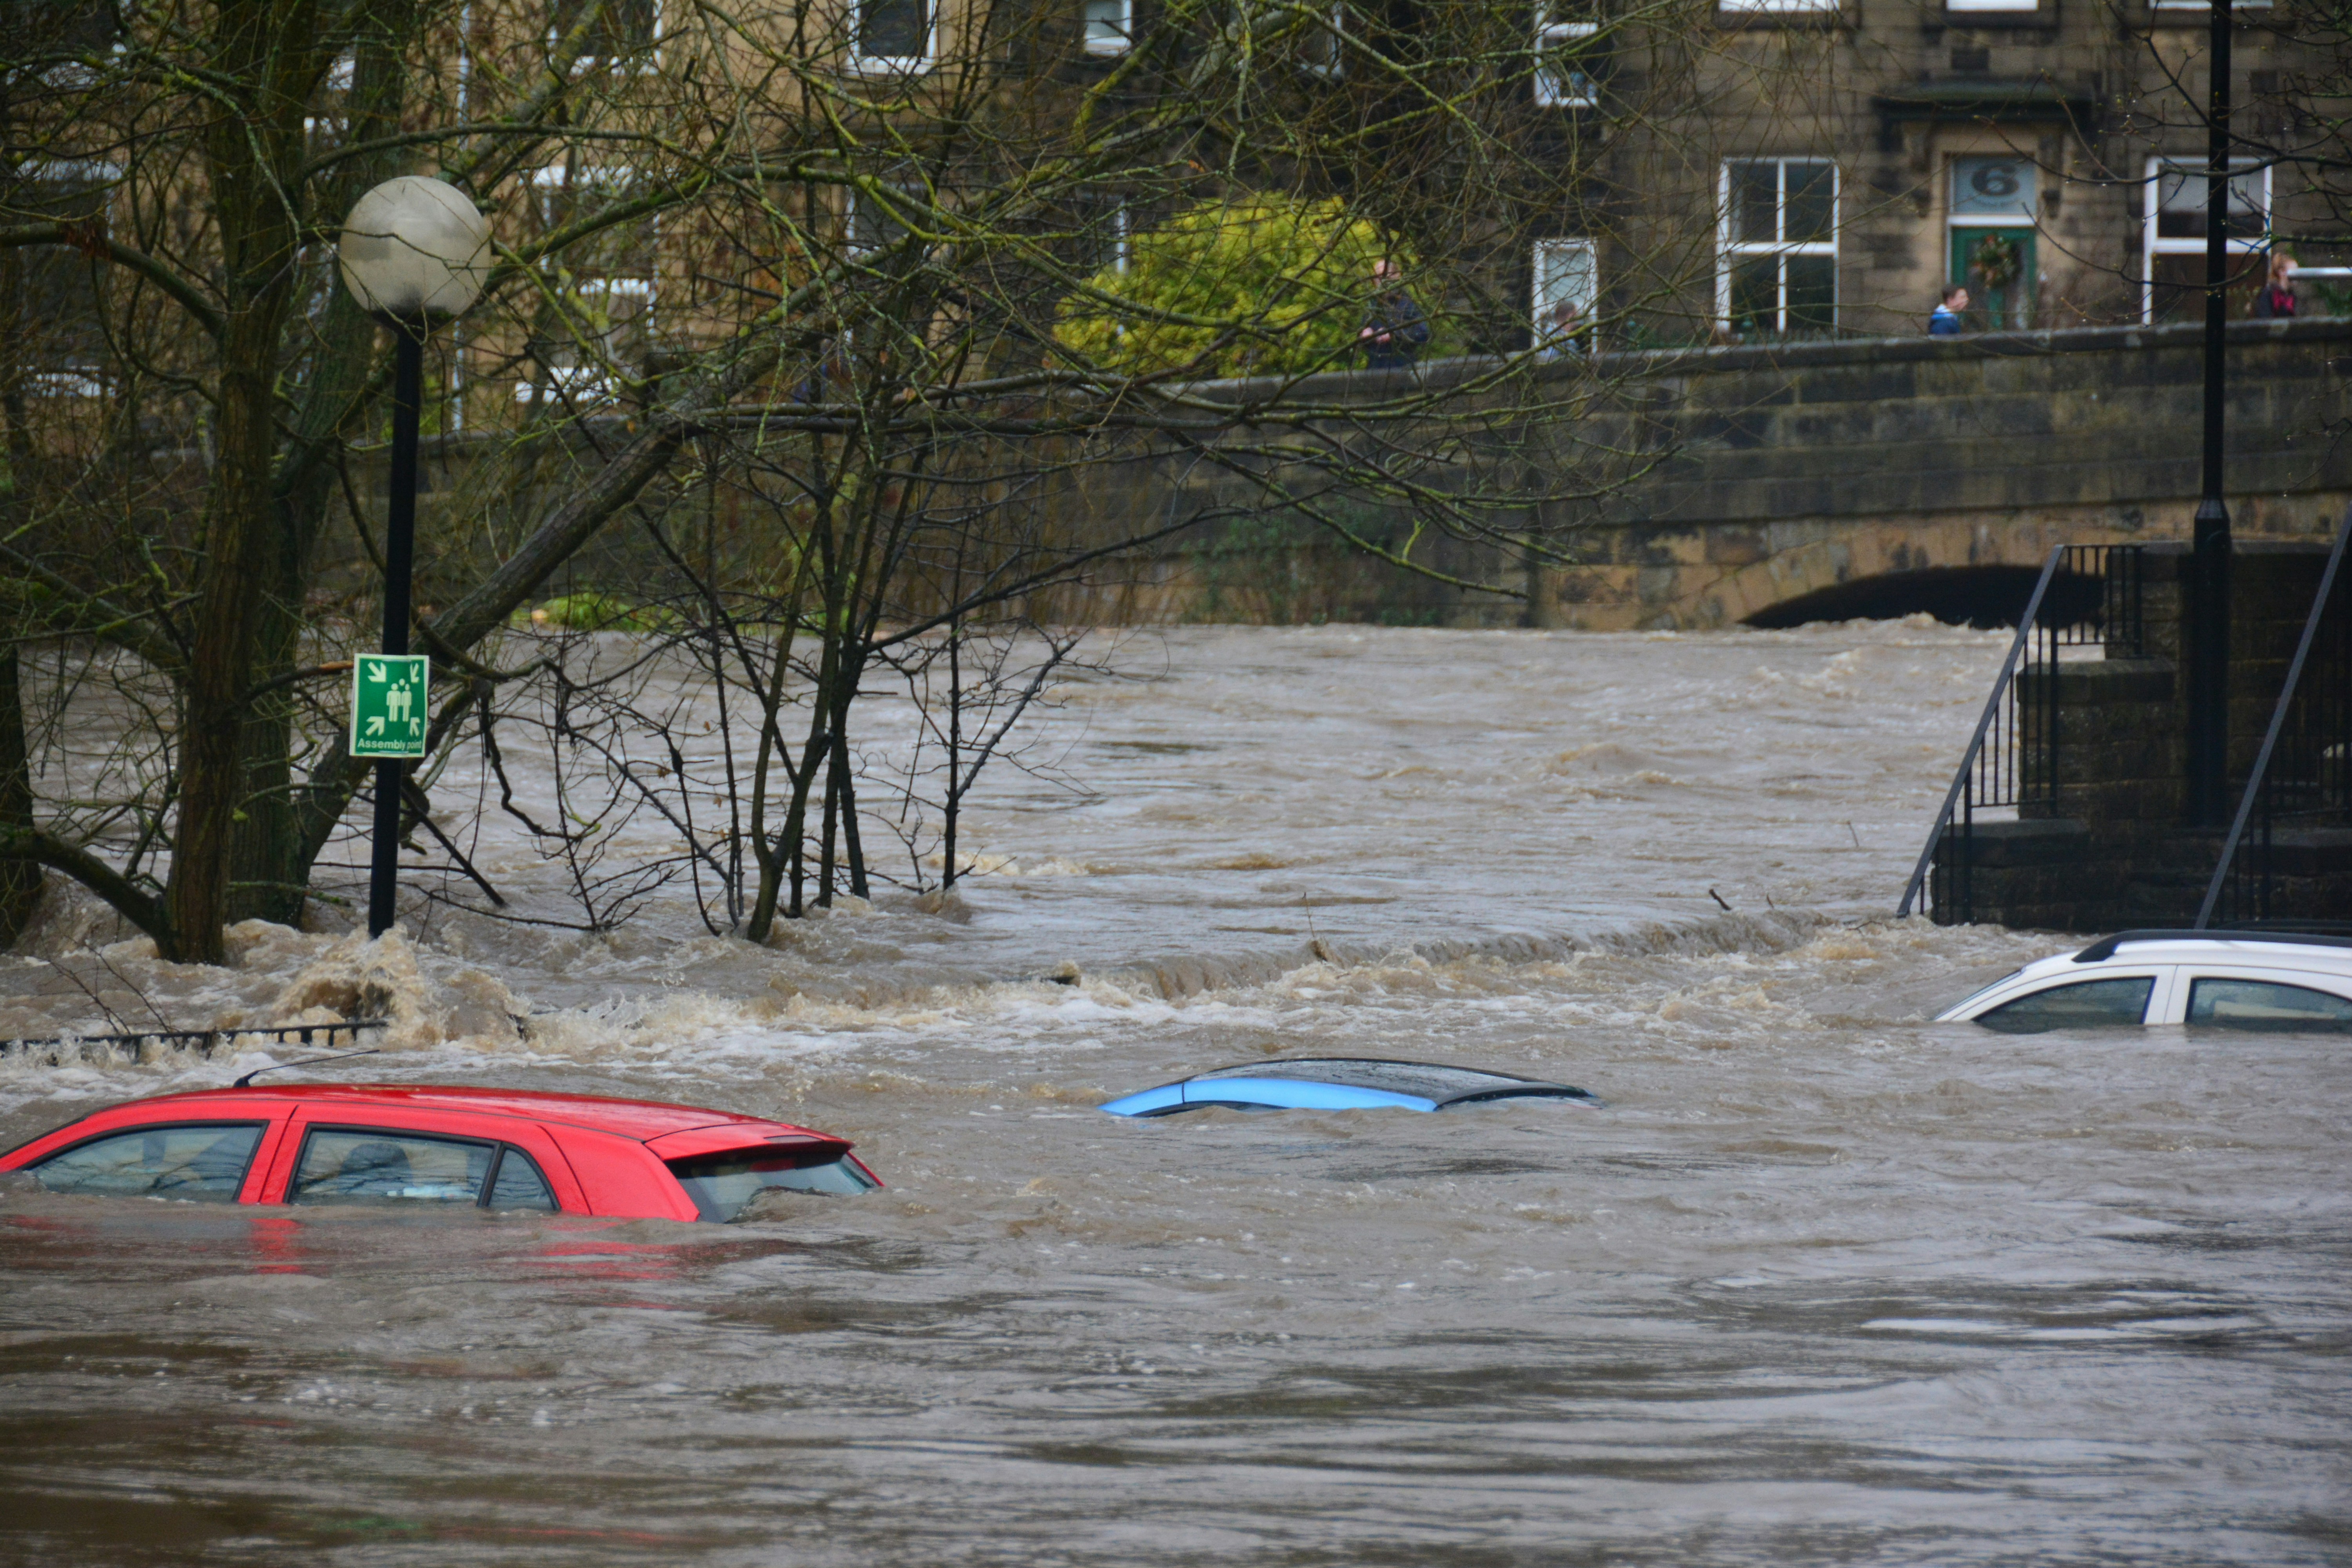
When homeowners evaluate their property for an accessory dwelling unit, they usually focus on backyard setbacks, tree roots, and electrical service. But if your parcel touches a river basin, coastal lowland, storm retention wash, or designated drainage corridor, another major regulatory hurdle appears: building an adu flood zone project.
Direct Answer:
Yes, you can generally build an ADU in a FEMA flood zone, but your project is governed by strict federal, state, and local floodplain management regulations. If your property lies within a 100-year Special Flood Hazard Area (such as Zone A or AE), your ADU cannot use a standard slab-on-grade foundation. The lowest finished floor, electrical panel, and HVAC equipment must be elevated to or above the local Base Flood Elevation (BFE) plus mandated municipal "freeboard" (typically 1 to 2 feet above BFE). Furthermore, properties located inside a designated regulatory floodway face severe construction restrictions or total prohibitions.
Before purchasing pre-drawn stock blueprints or commissioning custom architectural documents, conducting a comprehensive flood hazard audit will save you thousands of dollars in engineering redesigns.
Understanding FEMA Flood Zones on Your Parcel
The Federal Emergency Management Agency (FEMA) publishes Flood Insurance Rate Maps (FIRMs) that delineate flood risk across every incorporated municipality in the United States. When evaluating an adu floodplain location, your lot will fall into one of three primary flood risk classifications.
| FEMA Flood Zone | Hazard Level | 100-Year Flood Risk (1% Annual Chance) | Building Elevation Mandated? | Standard ADU Feasibility |
|---|---|---|---|---|
| Zone X (Unshaded) | Minimal Risk | Outside 500-year floodplain (less than 0.2% annual chance) | No | Excellent; standard slab or crawl space allowed |
| Zone X (Shaded) | Moderate Risk | 500-year floodplain (0.2% to 1% annual chance) | Rarely (subject to local bylaws) | High; standard foundation usually permitted |
| Zone A / AE | High Risk (SFHA) | 100-year base flood hazard (1% annual chance) | Yes (Must elevate above BFE + freeboard) | Feasible with custom engineered foundation |
| Zone AH / AO | High Risk (Shallow) | Shallow ponding or sheet flow (1 to 3 feet deep) | Yes (Elevate above specified flood depth) | Feasible with elevated stem walls or fill |
| Zone V / VE | Severe Coastal Hazard | 100-year coastal flood with high-velocity storm waves | Yes (Elevate on open pilings/stilts) | Complex; requires coastal structural engineering |
| Regulatory Floodway | Critical Hydraulic Zone | Active discharge channel of a stream or river | Prohibited without complex No-Rise study | Extremely low; habitable structures usually banned |
Zone X vs. Special Flood Hazard Areas (SFHA)
If your property is situated entirely within Zone X (unshaded), your ADU is subject only to standard municipal building codes. You can pour a traditional monolithic concrete slab or build a standard wood-framed crawl space without specialized flood documentation.
However, if your parcel touches a Special Flood Hazard Area (Zones A, AE, AH, AO, or VE), federal National Flood Insurance Program (NFIP) building standards are automatically triggered. Under federal law (44 CFR Section 60.3), any new residential construction in an SFHA must be designed to withstand hydrodynamic and hydrostatic flood forces.
The Regulatory Floodway: The Red Line of Construction
Every river or creek floodplain consists of two distinct zones: the flood fringe and the regulatory floodway.
The regulatory floodway is the deepest, fastest-flowing central channel of the waterway that must remain unobstructed to carry floodwaters downstream. Under federal regulations, no new construction, structural fill, or encroachment is permitted within a regulatory floodway unless a registered professional civil engineer conducts a rigorous hydraulic and hydrologic analysis demonstrating that the proposed ADU will cause zero increase in upstream flood elevations (known as a "No-Rise Certification"). Because achieving a No-Rise determination on a residential backyard lot is technically and financially daunting, most municipal floodplain administrators will immediately deny ADU permits inside a designated floodway.
The Four Separate Checks Every Homeowner Must Make
Homeowners frequently make the mistake of asking their local building department a single question: "Is my house in a flood zone?"
Floodplain feasibility requires four distinct technical checks. A property can be technically inside an AE zone but naturally elevated on high ground, or outside the flood zone while lacking dry emergency vehicle access.
| Verification Check | Technical Term | What It Measures | How It Impacts Your Project |
|---|---|---|---|
| 1. Map Zone Check | FEMA Flood Zone Designation | Statistical probability of seasonal flooding (e.g., Zone AE vs Zone X) | Dictates whether federal NFIP building standards apply |
| 2. Elevation Check | Base Flood Elevation (BFE) vs Natural Ground | The calculated water surface height during a 100-year storm | Determines how many feet your ADU must be elevated above the dirt |
| 3. Access Route Check | Dry Access / Egress Clearance | Elevation of driveways and streets leading to the parcel | Emergency responders must be able to reach the unit during floods |
| 4. Channel Boundary Check | Regulatory Floodway Limit | Exact distance from active stream discharge channel | Determines whether building is legally possible or entirely barred |
1. Map Zone Verification
Never rely on casual assurances from real estate listings or online consumer maps. You must look up your official property boundaries directly on the FEMA Flood Map Service Center (MSC) using your parcel number or street address. Identify the exact letter designation covering your proposed backyard building footprint.
2. Base Flood Elevation (BFE) and Freeboard
The Base Flood Elevation (BFE) represents the projected height of floodwaters during a flood that has a 1 percent annual chance of occurrence (often called the 100-year flood).
In addition to federal BFE baselines, most flood-prone municipalities enforce a local freeboard requirement. Freeboard is an additional safety buffer (typically 1, 2, or 3 feet) added on top of the BFE to account for future sea level rise, urban development runoff, and wave action.
- If your natural ground sits at an elevation of 42 feet above sea level, your BFE is 44 feet, and your city enforces a 2-foot freeboard requirement, your ADU's lowest finished floor must sit at an elevation of at least 46 feet.
- That means your foundation must elevate the living space 4 feet above the existing ground.
3. Dry Vehicular Access
Even if your proposed ADU foundation can be elevated on tall concrete pilings to clear the BFE, many municipal fire and life-safety codes mandate "dry access." City building officials may reject an ADU permit if the driveway or public street leading to the backyard unit would be submerged under 3 feet of rushing water during a storm event, preventing fire engines and ambulances from evacuating tenants.
Why Pre-Approved (PRADU) Standard Plans Often Exclude Flood Zones
In recent years, forward-thinking cities across California, Washington, and Oregon have developed library catalogs of "pre-approved" or "permit-ready" ADU plans (PRADUs) to help homeowners fast-track municipal plan check.
However, almost every municipal standard-plan program explicitly disqualifies lots located within FEMA flood hazard zones. For example, the City of Riverside Community & Economic Development Department explicitly notes in its standard ADU plan eligibility guidelines that pre-approved architectural drawings cannot be utilized on properties mapped inside a designated flood zone.
| Pre-Approved (PRADU) Plan Limitation | Flood Zone Engineering Reality | Homeowner Solution |
|---|---|---|
| Generic Foundation Design | Standard plans specify 4" slab-on-grade for flat, dry terrain | Must engineer elevated stem walls, piers, or pilings |
| Missing Flood Openings | Stock plans lack hydrostatic vents required by FEMA | Custom placement of engineered flood openings |
| Fixed Equipment Mounting | Mechanical HVAC and water heating placed at ground level | Wall-mounted equipment platforms elevated above BFE |
| No Site-Specific BFE | Generic blueprints cannot calculate parcel flood heights | Licensed surveyor establishes true site elevation datum |
This restriction does not mean building an ADU is prohibited in these cities. It simply means you cannot use a generic, pre-drawn stock plan. You must hire a professional architectural and engineering design team to produce custom, site-specific construction documents that incorporate engineered flood mitigation measures.
Core Engineering Requirements: Foundations, Vents, and Mechanicals
Building a code-compliant residential dwelling inside an adu flood zone requires specific structural and civil details that must appear on your architectural plans:
| Structural Component | Mandatory Code Requirement | Typical Engineering Solution | Common Installation Pitfall |
|---|---|---|---|
| Finished Living Floor | Elevated to or above BFE + Freeboard | Stepped concrete stem walls, structural fill, or open pilings | Measuring to the bottom of the joist instead of top of finished floor |
| Hydrostatic Flood Openings | Minimum 1 sq in net vent area per 1 sq ft enclosed space | FEMA-compliant engineered flood vents in foundation walls | Installing standard insect crawl space vents that do not allow water flow |
| Mechanical Equipment (HVAC) | All electrical/mechanical components elevated above BFE | Cantilevered exterior equipment platform or roof-mount mini-split | Placing ground-level AC condenser pad in the dirt below flood level |
| Water Heating & Laundry | Tank and electrical connections elevated | Interior utility closet raised on elevated platform | Installing floor-mounted water heater on low foundation slab |
| Electrical Service Panels | Main breaker and subpanels above flood line | Subpanel mounted at 5 ft or higher on exterior ADU wall | Running low-level underground conduits that flood during storms |
| Sewer Lateral Protection | Prevent municipal sewer backflow into ADU | Dual-flapper backwater check valve installed on main sewer line | Relying on gravity flow without municipal backflow prevention |
1. Foundation Options for Flood Zones
A standard monolithic concrete slab poured on native soil is not permitted in a Special Flood Hazard Area unless the entire building pad is raised with engineered structural fill dirt. Structural engineers generally specify one of three foundation systems:
- Elevated Stem Wall with Crawl Space: Reinforced concrete or concrete masonry unit (CMU) stem walls raise the floor framing above the flood elevation. The enclosed crawl space beneath the home is designed to flood intentionally during a storm, equalizing water pressure on both sides of the concrete walls.
- Engineered Hydrostatic Flood Vents: Under FEMA Technical Bulletin 1, foundation walls enclosing space below the BFE must include automatic flood openings. These vents must provide at least 1 square inch of net open area for every 1 square foot of enclosed crawl space. The bottom of each vent must sit no higher than 12 inches above adjacent grade, and a minimum of two vents must be installed on opposite exterior walls.
- Elevated Open Pilings or Columns: In coastal Zone VE or high-velocity Zone AE areas, homes must sit atop open reinforced concrete piers or heavy treated timber pilings, allowing flood surges and waves to pass beneath the building without exerting lateral structural force. To compare foundation systems and relative costs, read our comprehensive guide on ADU foundation types and costs.
2. Elevating Mechanical, Electrical, and Plumbing (MEP) Equipment
One of the most frequent reasons building inspectors fail flood-zone ADUs at final inspection is ground-mounted mechanical equipment:
- Ductless mini-split heat pump compressors cannot sit on a standard ground-level concrete pad; they must be mounted on heavy-duty cantilevered steel brackets bolted to the ADU exterior wall above the BFE.
- Tankless or heat pump water heaters must sit inside an elevated utility closet.
- Electrical subpanels and wiring junction boxes must be installed above the freeboard line.
Elevation Certificates and Flood Insurance Economics
Two financial and documentation realities dictate whether an ADU in a flood zone makes long-term economic sense: the Elevation Certificate and annual flood insurance premiums.
| Milestone Phase | When It Occurs | Professional Responsible | Why It Is Mandatory |
|---|---|---|---|
| Pre-Construction Elevation Certificate | During architectural design (based on plans) | Licensed Land Surveyor or Civil Engineer | Submitted to city plan check to prove proposed building height satisfies BFE |
| Finished Construction Elevation Certificate | After foundation is poured and framed | Licensed Land Surveyor | Required by city building inspector before issuing Certificate of Occupancy |
| NFIP Flood Insurance Policy | Before tenant moves in | Independent Insurance Agent | Protects the capital investment; mandatory for federally backed mortgages |
The FEMA Elevation Certificate (FEMA Form 086-0-33)
An Elevation Certificate is an official administrative document completed by a licensed land surveyor. The surveyor shoots precise elevation laser shots on your property, documenting natural ground elevation, lowest adjacent grade, highest adjacent grade, and the exact top-of-finished-floor elevation. You will need to budget $1,500 to $2,500 for surveying fees to cover both the pre-construction plan review and post-construction certification.
The Impact on Homeowners and Flood Insurance
Standard homeowners insurance policies explicitly exclude flood damage caused by surface water inundation or overflowing rivers. To protect your ADU structure and tenant improvements, you must purchase a dedicated flood insurance policy through the National Flood Insurance Program (NFIP) or a private surplus-lines carrier.
Under FEMA's updated rating system (Risk Rating 2.0), flood insurance premiums are calculated based on your structure's exact elevation relative to the Base Flood Elevation:
- Building Right at BFE: Can result in annual flood insurance premiums ranging from $1,800 to $3,500 per year.
- Building 2 to 3 Feet Above BFE (Adding Freeboard): Can drop your annual premium down to $600 to $1,200 per year, saving tens of thousands of dollars over the lifetime of the property. For a complete analysis of property risk and landlord coverage options, see our guide on ADU insurance requirements.
The "VERIFY" Protocol: When a Parcel Can Be Removed from the Flood Zone
Occasionally, official FEMA flood maps show an entire parcel in Zone AE, even though a portion of your backyard sits high and dry on a natural natural ridge well above the flood boundary. In these situations, the project status remains VERIFY.
| Resolution Path | Site Elevation Finding | Action Required | Permitting & Foundation Outcome |
|---|---|---|---|
| Path A: Confirmed Floodplain | Natural ground sits below BFE | Custom architectural and structural engineering | Elevated foundation, flood vents, elevated mechanicals |
| Path B: Letter of Map Amendment (LOMA) | Natural ground sits above BFE | Surveyor submits electronic eLOMA to FEMA | Reclassified to Zone X; standard slab foundation permitted |
| Path C: Regulatory Floodway or Severe Hazard | Footprint touches floodway or violates height limits | Relocate footprint away from wash or cancel build | Avoids wasted drafting fees on unbuildable parcels |
If your surveyor's elevation shots prove that the natural ground elevation of your proposed ADU footprint sits above the Base Flood Elevation, you can submit an application to FEMA for a Letter of Map Amendment (LOMA):
- A LOMA is an official administrative document issued by FEMA that formally amends the effective flood map.
- It legally reclassifies your specific building pad from a Special Flood Hazard Area (Zone AE) to low-risk Zone X.
- Obtaining an approved LOMA eliminates mandatory flood foundation engineering, exempts the unit from mandatory federal flood insurance purchase requirements, and allows you to build a cost-effective slab-on-grade foundation. Processing a LOMA typically takes 6 to 10 weeks and costs $1,500 to $3,000 in professional surveyor fees.
Homeowner Checklist: Information to Gather Before Design
Before spending money on architectural floor plans, gather these five critical data points regarding your lot's flood status:
- 1. Download the Official FEMA FIRMette: Visit the FEMA Flood Map Service Center online. Search your parcel address, create an official scaled "FIRMette" PDF map, and print out the legend showing your exact zone designation.
- 2. Check for a Regulatory Floodway: Inspect the FIRMette map to verify whether your backyard touches the cross-hatched "Regulatory Floodway" channel of any nearby creek, river, or wash.
- 3. Consult Your Local Floodplain Administrator: Call your city or county building department and ask to speak with the Floodplain Administrator. Inquire about the exact Base Flood Elevation for your parcel and ask how many feet of local freeboard the city mandates.
- 4. Check Existing House Elevation Records: Ask your title company or local building department if an existing Elevation Certificate is on file for your primary home. This historical document provides exact benchmark elevations for your parcel.
- 5. Review Height Limit Interactions: Check your local zoning code's maximum ADU height restriction. If your city caps ADUs at 16 or 18 feet, and your foundation must elevate the living floor 4 feet above the ground to clear the BFE, verify that your roof ridge can still fit under the municipal height ceiling.
How Build With A Plan Evaluates Your Property Feasibility
Designing an accessory dwelling unit in a flood zone without verifying FEMA map boundaries and Base Flood Elevations leads to instant permit rejection, wasted design fees, and uninsurable buildings.
At Build With A Plan, we examine site feasibility before you invest in expensive construction drawings:
The Backyard Wealth Package:
We turn your backyard into a rental unit. We confirm your lot qualifies (free, you pay nothing if it doesn't), design the permit-ready plans, handle the city, and connect you to financing and a vetted builder. $6,000 flat, about what an architect charges just to start.
Our Clear Deliverables Guarantee
We guarantee your architectural drawings will be accepted for submission by your city, or we revise them free until they are. And if your property doesn't pass our free feasibility check, you pay nothing.
Our team audits FEMA flood zone maps, reviews local freeboard ordinances, checks regulatory floodway proximity, and coordinates with licensed land surveyors to establish true site elevations before drafting begins. Where custom structural engineering, elevated stem walls, or hydrostatic flood vents are required, we incorporate code-compliant details directly into your permit package. We won't even take your money unless your property qualifies.
Find out if your property has a buildable, permit-ready path for an ADU. Request your free property feasibility check today and get a clear, professional assessment of your site.
Frequently Asked Questions
Can I build an ADU in a flood zone with a concrete slab-on-grade foundation?
In a designated 100-year Special Flood Hazard Area (Zone A or AE), pouring a standard monolithic slab directly on native ground is generally prohibited. The finished living floor must be elevated to or above the Base Flood Elevation plus local freeboard. The only way to use a slab-on-grade foundation in a flood zone is to import engineered structural fill dirt to raise the entire building pad above the flood elevation, which requires civil grading permits, compaction testing, and approval from the local Floodplain Administrator.
What is the difference between a flood zone and a floodway?
A flood zone (such as Zone AE) represents the broader geographic area expected to be inundated during a 100-year storm event. Construction is allowed in flood zones provided the building is elevated above the floodwaters. A regulatory floodway is the central, deep channel of a river or stream that carries the rushing flood discharge. Building a habitable residential ADU within a regulatory floodway is almost universally prohibited under federal and municipal code because any physical structure obstructs flood conveyance and pushes water higher onto neighboring properties.
Does building an ADU in a flood zone increase my property insurance costs?
Yes. Standard homeowner policies do not cover flood damage. If your property carries a federally backed mortgage and sits in an SFHA, federal law mandates flood insurance coverage. A detached ADU is legally classified as a separate building under National Flood Insurance Program (NFIP) guidelines and requires its own dedicated flood policy. Elevating your ADU 2 to 3 feet above the Base Flood Elevation (incorporating extra freeboard) significantly reduces annual insurance premiums.
Can an existing detached garage in a flood zone be converted into an ADU?
Converting an existing garage in a flood zone into an ADU is exceptionally challenging. Under NFIP regulations, non-habitable accessory buildings (like vehicle parking garages) can have floor slabs below the BFE, provided they feature flood vents. However, once you convert that space into a habitable residential dwelling (adding a kitchen and bedroom), the entire finished floor must be elevated to or above the BFE. Unless the existing garage slab was originally poured above the flood elevation, you would have to reconstruct the foundation or pour an elevated structural floor system inside the garage.
How long does it take to obtain a FEMA Letter of Map Amendment (LOMA)?
If a licensed land surveyor determines that your proposed building site sits on natural high ground above the Base Flood Elevation, submitting an electronic LOMA application (eLOMA) through FEMA's online portal typically takes 6 to 10 weeks for official review and issuance. Once approved, the LOMA legally reclassifies the building footprint into low-risk Zone X, eliminating mandatory flood foundation engineering and federal flood insurance purchase requirements.